Best super app in France: Ozapay vs Deblock, Phantom, WeChat, and Revolut
Ozapay, Deblock, Phantom, WeChat, or Revolut: compare payments, self-custody, messaging, and services for individuals and professionals in France.
Read more
For several years, a new concept has been emerging in the technology industry: that of super-apps\n\nAfter WeChat, Grab, Alipay, or even Elon Musk's ambitions with X Money, it is now Microsoft that is presenting Copilot as its future super-app dedicated to artificial intelligence.\n\nBut this announcement raises an essential question:\n\nCan we really talk about a super-app?\n\n---\n\n# Microsoft brings together all its AI services\n\nMicrosoft has announced a major evolution of Copilot.\n\nThe goal is to gradually bring together several artificial intelligence experiences within a single application:\n\n- Copilot Chat\n- GitHub Copilot\n- Copilot Pages\n- Copilot agents\n- Microsoft 365 productivity tools\n\nThe idea is simple: offer a single entry point allowing users to access all artificial intelligence services developed by Microsoft.\n\nAt first glance, this strategy is reminiscent of super-apps.\n\nBut in reality, the comparison deserves nuance.\n\n---\n\n# A centralization of services rather than a true super-app\n\nAt OZAPAY, we believe that this evolution corresponds more to a centralization of services than to a true super-app.\n\nWhy?\n\nBecause all applications grouping several features do not automatically become super-apps.\n\nCopilot efficiently brings together several artificial intelligence tools.\n\nBut its goal remains focused on a very specific universe:\n\n- AI assistance;\n- productivity;\n- software development;\n- intelligent agents.\n\nIn other words, Microsoft unifies its offering, but stays within the same family of services.\n\n---\n\n# What is a true super-app?\n\nFor us, a true super-app goes far beyond simple feature integration.\n\nIt accompanies the user in their daily life.\n\nIt allows for example to:\n\n- communicate;\n- send and receive money;\n- make payments;\n- purchase goods or services;\n- book transportation or accommodation;\n- manage their digital identity;\n- access third-party partners;\n- interact with a real ecosystem.\n\nThe goal is not just to bring tools together.\n\nIt is to become the application the user naturally opens several times a day, whatever their need.\n\nThis is precisely what distinguishes platforms like WeChat, Grab or Alipay.\n\n---\n\n# The real trend: reducing fragmentation\n\nThis does not mean Microsoft is wrong.\n\nOn the contrary.\n\nThe announcement confirms a trend that we observe among all major technology players.\n\nUsers want fewer applications and more integrated experiences.\n\n- Apple is gradually bringing all its services closer together.\n- Google is developing an increasingly coherent ecosystem around Gemini.\n- Microsoft is now centralizing its Copilot universe.\n\nAll these companies are pursuing the same objective:\n\nReduce the fragmentation of digital usage.\n\n---\n\n# The next step will be the most interesting\n\nIn our view, the next evolution will no longer consist only of bringing several tools together under the same interface.\n\nPlatforms will seek to connect:\n\n- artificial intelligence;\n- payments;\n- digital identity;\n- financial services;\n- commerce;\n- communication;\n- partner services.\n\nThis is when we will be able to really talk about universal super-apps.\n\n---\n\n# Why this distinction matters\n\nThe term super-app is now widely used.\n\nYet, not all integrated platforms meet this definition.\n\nWe now distinguish three major categories.\n\n## 1. Unified platforms\n\nThey group several services belonging to the same universe.\n\nExamples:\n\n- Microsoft Copilot\n- Adobe Creative Cloud\n- Microsoft 365\n\n## 2. Digital ecosystems\n\nThey connect several families of products and services.\n\nExamples:\n\n- Apple\n- Google\n\n## 3. True super-apps\n\nThey become a single entry point for a multitude of daily needs, while integrating third-party services.\n\nExamples:**\n\n- WeChat\n- Grab\n- Alipay\n\n---\n\n# Our vision at OZAPAY\n\nWe are convinced that the future does not lie in the accumulation of features, but in their smart integration.\n\nA super-app should not simply offer more tools.\n\nIt must simplify the lives of its users by bringing together, within a single experience, the services they actually use on a daily basis.\n\nMicrosoft's announcement is excellent news for the industry.\n\nIt confirms that large companies are now seeking to build increasingly complete and coherent platforms.\n\nBut in our view, the next generation of super-apps will go even further, by connecting artificial intelligence, payments, digital identity, partners and everyday services in a truly open ecosystem.\n\nThe future will probably not be an application containing more features.\n\nIt will be an application capable of naturally replacing several applications at once, while offering a smooth, secure and useful experience on a daily basis.
By Johan Decottignies
Ozapay, Deblock, Phantom, WeChat, or Revolut: compare payments, self-custody, messaging, and services for individuals and professionals in France.
Read more
The vote on 2027 budget revenue has been postponed to November 3. A welcome opportunity to examine the consequences of taxing certain stablecoin conversions. And to save parliamentarians time, Ozapay has already prepared the reading.
Read more
The major Revolut outage on October 20, 2026 is reigniting the debate over our dependence on digital banks. Discover why self-custody and Web3 technologies are opening new perspectives, and how OZAPAY aims to contribute to this evolution.
Read more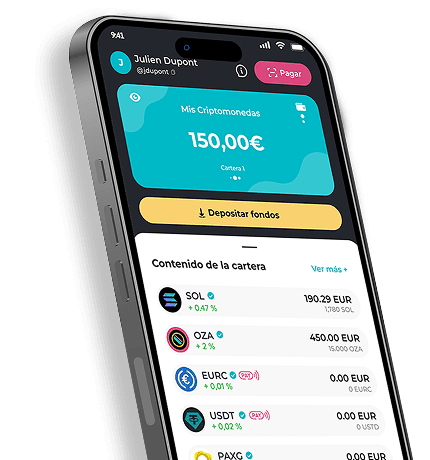
JOIN
OZAPAY
AND GET €5 IN OZA!
The crypto app made for you
Use this code when you sign up
OZABRAAlready registered?Log in
Your money, your rules.
Pay, send and receive in full freedom.
Disclaimer: Buying and holding OZA tokens involves a risk of partial or total loss of the invested capital. Links to Raydium and Coingecko are provided solely to make access to market information and third-party trading tools easier — Ozapay does not manage them and is not responsible for them. OZA is neither a financial instrument, nor a bank deposit, nor a regulated savings product. Crypto-assets are volatile and not covered by legal guarantees, so it is recommended to invest only amounts you are prepared to lose and, if needed, consult a financial advisor before any decision. Access to OZA may be subject to legal restrictions depending on your country of residence. The OZA token is not offered to the public in France within the meaning of Regulation (EU) 2023/1114. Token address: 67iVSrbgQKiPjttU9uXx9CXUoS1Si3XUhrXeiNAUUZSR. This site does not constitute a public offer of crypto-assets. No AMF visa has been requested or obtained.
© All rights reserved to Ozapay - The payment Super App
